Revised rules for intra-group loans through Cyprus

International Tax Review is part of Legal Benchmarking Limited, 1-2 Paris Garden, London, SE1 8ND

Copyright © Legal Benchmarking Limited and its affiliated companies 2026

Accessibility | Terms of Use | Privacy Policy | Modern Slavery Statement


Revised rules for intra-group loans through Cyprus

After years of negotiations between the Inland Revenue Department and the Institute of Certified Public Accountants of Cyprus, the Commissioner of Income Tax has clarified in writing the conditions that needs to be satisfied in back to back financing arrangements involving a Cyprus entity as intermediary company.

null

Giannos Ioannou

Cyprus Financing Companies (CFCs) are commonly used in international tax structuring mainly due to the wide range of tax related benefits they have to offer. The advantages that have made Cyprus a favourable financing company jurisdiction for investors and it is considered a major vehicle for international tax planning are based on two main reasons:

  • Firstly, due to the country's flexible tax system;

  • Secondly, the existence of the DDT between Cyprus and many countries that limits withholding taxes.

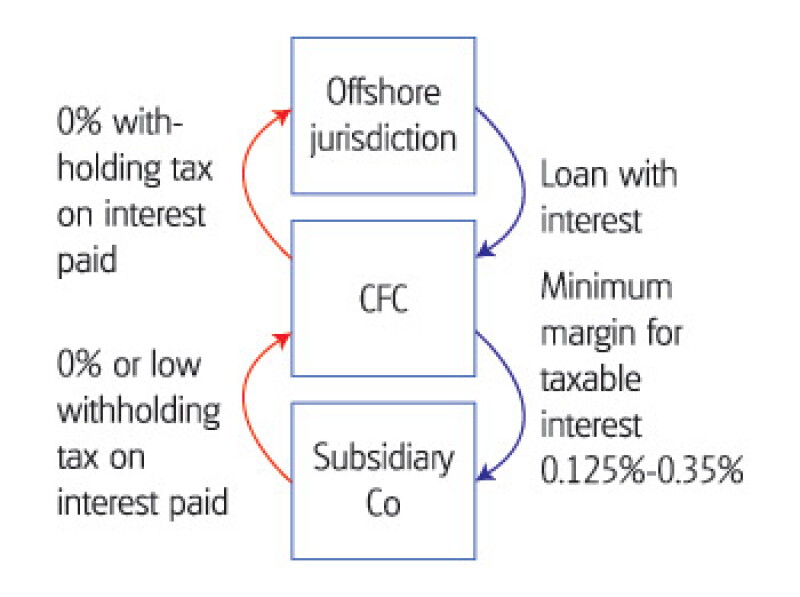
Diagram 1

null

According to the Commissioner, the minimum interest margins to be accepted by the Department of Inland Revenue would be determined based on the loan amount as shown in Table 1.

Interest free loan agreements would be subject to a deemed interest margin of 0.35% and shall apply irrespective of the loan amount.

The above margins are applicable for the tax years 2008 onwards. For the tax years 2003-2007 the acceptable margin is 0.3% irrespective of the amount and whether it is interest bearing.

The above margins apply when Cyprus companies are used as intermediary financial vehicles to finance other related or connected companies and the following conditions are satisfied:

  • The funds borrowed should be used within a six-month period;

  • The write off of any loans should not create any tax benefit or tax liability for the Cyprus company.

Table 1

Loan amount

Interest bearing loans

Interest free loans

EURO

%

%

Up to 50 millions

0.35

0.35

From 50 millions up to 200 millions

0.25

0.35

More than 200 millions

0.125

0.35


The above also applies when the funds are borrowed by a bank and the loan facility as guaranteed by other related or connected companies.

In line with the above, the use of Cyprus as a Financing Company minimises the tax implications which are further reinforced by the recent clarifications on the definition of minimum/maximum interest margin.

Intra-group loans by the use of an intermediary CFC minimises the tax luggage carried forward due to minimum margin frames and no withholding taxes on interest paid are imposed.

Giannos Ioannou (giannos.ioannou@eurofast.eu)

Eurofast Taxand, Cyprus

Tel: +357 22 699 222

Website: www.eurofast.eu

more across site & shared bottom lb ros

More from across our site

Awards
It was also a memorable night for Baker McKenzie and its associated firms, after picking up 19 awards, including the coveted Asia-Pacific Tax Law Firm of the Year
Stocche Forbes Advogados, Utumi Advogados and Lobo de Rizzo Advogados have reached Tier 2 as competition intensifies in the region’s largest tax market
Ben Webster’s arrival represents a significant expansion of Withers’ London tax litigation practice, as the private client firm eyes further international growth
The combination swiftly builds on RSM’s addition of a new Lithuanian firm to its international network, signalling a European build-out
Tax teams must look beyond pillar two’s headline rules as R&D incentives and the US side-by-side deal create new strategic choices for multinationals, says Marta Pankiv of Tricentis
As funds work becomes more complex, Proskauer is betting that embedded tax expertise can strengthen its wider offering
The recently founded AI platform stands out in a crowded marketplace thanks to a compelling vision and friends in the right places
Advisers expect consumption tax reform to stay on course, but debt pressures could push the government towards tougher enforcement and incentive reviews
The firm demonstrated its sweet spot of litigation with an international twist with the recent win for the Danish tax authority…but it’s not a tax case
The recently formed firm has taken a break from hiring EY talent to expand its transactional tax and tax technology capabilities
Gift this article