
Timeline leading to the Interest and Royalties Directive |
| Early 1990s: Europe realized that it was necessary to promote the implementation of a common market by removing the hurdles to economic transactions involving companies in different member states. July 23 1990: the Commission adopted the Parent-Subsidiary Directive and the Merger Directive. December 6 1990: the Commission presented the Council with a proposal for a directive on a common system of taxation applicable to interest and royalty payments between associated companies in different member states. June 3 2003: the Council of the European Union (EU) adopted Directive 2003/49/EC on the common tax rules for payments of interest and royalties made between associated companies in different member states, the so-called Interest and Royalties Directive (IRD). January 1 2004: The deadline for existing member states to bring their national laws into line with the IRD. May 1 2004: The deadline for the 10 acceding member states (accession date) to bring their national laws into line with the IRD, unless they benefit from transitional periods. |
The rationale of the European Commission's proposal on December 6 1990 (see box opposite) for a directive on a common system of taxation applicable to interest and royalty payments between associated companies in different member states was that interest and royalties should be taxed in one member state only. Indeed, despite unilateral measures and tax treaties, double taxation still existed in quite some cases.
Moreover, tax at source, though recoverable at a later stage, can result in an upfront financing of the tax, which constitutes a burden for the taxpayers concerned.
After 13 years, the Commission's work in this area finally resulted in Directive 2003/49/EC, which should offer the following improvements:
recovering of the withholding tax (WHT) is no longer an issue;
no upfront financing of tax; and
relatively simple formalities.
The Interest and Royalties Directive - conditional exemption regime
Principle
Under the IRD, interest and royalty payments arising in member state A are exempted from any tax (by deduction at source or by assessment) in member state A, provided that the beneficial owner of the interest or royalties is a company of member state B or a permanent establishment (PE) situated in member state B of a company of another member state. The taxation prerogative is therefore in principle entirely attributed to member state B.
Scope ratione materiae
The IRD defines "interest" and "royalties" broadly:
Interest: income from debt-claims of every kind, whether or not secured by mortgage and whether or not carrying a right to participate in the debtor's profits, and in particular, income from bonds or debentures, including premiums and prizes attaching to such securities, bonds or debentures. Penalty charges for late payment are not regarded as interest;
Royalties: payments of any kind received as a consideration for the use of, or the right to use, any copyright of literary, artistic or scientific work, including cinematograph films and software, any patent, trade mark, design or model, plan, secret formula or process, or for information concerning industrial, commercial or scientific experience. Payments for the use of, or the right to use, industrial, commercial or scientific equipment shall also be regarded as royalties.
Scope ratione materiae
The companies between which payments of interest and royalties are made have to be associated companies of different member states.
Company of a member state
The companies qualifying under the IRD have to be:
incorporated in one of the forms set out in the (limitative) annex to the IRD;
tax resident in a member state, and;
subject to one of the taxes mentioned in the IRD without being exempt (in essence, corporate income tax).
Beneficial owner
A company shall be treated as the beneficial owner of the interest or royalty only if it receives those payments for its own benefit and not as an intermediary, such as an agent, trustee or authorized signatory, for some other person.
Associated companies - the holding condition
A company is to be regarded as an associated company of another company where:
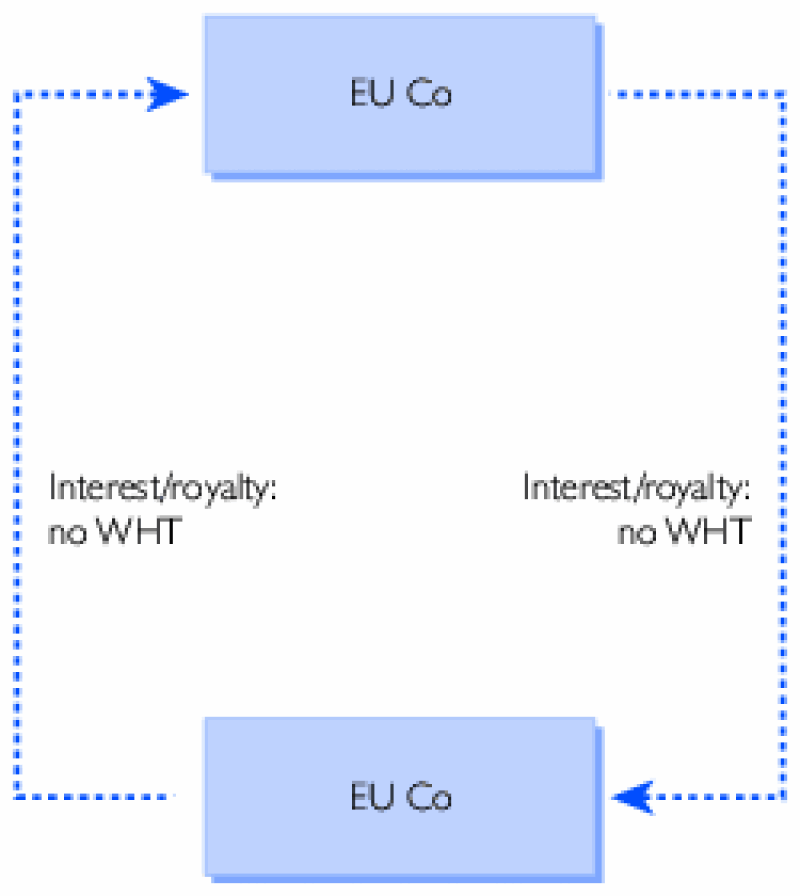
it has a direct minimum holding of 25% in the capital of the other company (or inversely) (see diagram 1), or;
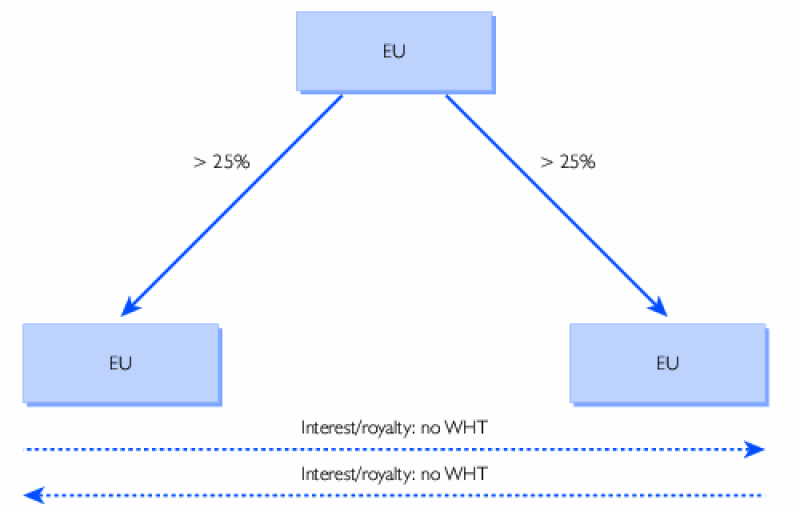
a third company situated in a member state has a direct minimum holding of 25% both in its capital and in the capital of the other company. Although not explicitly mentioned in the IRD, it is the common understanding that the third company (common parent) should also be an EU company (see diagram 2).
The IRD as such only applies to cross-border payments. However, it can be questioned whether WHT can be imposed on income paid to a resident company in cases where an exemption is granted for the same payment to a non-resident EU company. Taking into account Leur-Bloem case law, we think this would constitute a discrimination incompatible with EU law.
To determine whether the 25% holding threshold is achieved, only direct holdings are taken into account as opposed to the draft directive, which also included indirect participations. This is a regrettable amendment, as the IRD is only applicable in limited cases of direct participation link, unless a broader implementation is enacted - see examples of Belgium and Slovenia below - and hence only partially reaches its objective of doing away tax hurdles on intercompany interest and royalty flows.
Diagram 1: Associated companies (1) |
|
Diagram 2: Associated companies (2) |
|
Permanent establishments
The IRD does not apply to situations where interest or royalties are paid by or to a non-EU permanent establishment of a EU company, and the business of the company is wholly or partly carried on through that PE.
Furthermore, a PE paying interest or royalties will only benefit from the IRD insofar as those payments represent a tax-deductible expense for the PE in the member state in which it is located.
Holding condition - waiting or retention period?
The IRD gives an option for the source state to refuse the benefit of the IRD where the holding condition has not been fulfilled for an uninterrupted period of at least two years.
The IRD is not very clear on whether this condition has to be satisfied at the time the interest/royalty is attributed or made payable (waiting period) or whether it is enough for it to be satisfied after the moment the interest/royalty is attributed or made payable (retention period). The text of the IRD suggests that the option is left to the member states.
This is somewhat surprising: the Parent-Subsidiary Directive contains a similar provision, which gave rise to many discussions on whether it is a waiting period or a retention period. In its Denkavit judgment of October 17 1996, the European Court of Justice (ECJ) ended the controversy by deciding that it was a retention period.
To the extent that the two directives have a common objective and that the aim is to align the IRD to the Parent-Subsidiary Directive, one might wonder, given the Denkavit case, what impelled the Commission to allow an option to the member states for the IRD. This is especially relevant since, as we see below, for example, Slovenia and Lithuania intend to apply a waiting period.
Formalities
The source state can furthermore require that, at the time at which interest or royalties are paid, a certificate has to be produced testifying that the conditions have been met.
Anti-abuse measures
The IRD does not prevent the application by the member states of measures that they consider necessary to prevent fraud or abuse.
Excessive payments
The exemption laid down by the IRD is only applicable to a payment insofar as it does not exceed what would have been agreed between independent parties: the portion considered excessive will not qualify for the exemption under the IRD and the member states may levy a WHT on that portion.
Thin capitalization rules
The draft directive contained a possibility to grant the exemption only to debtors fulfilling a certain capitalization ratio. As this thin capitalization reference has not been retained in the final version of the IRD, one could question whether member states are allowed to apply domestic thin capitalization rules in case all IRD conditions are met. Indeed, a thin capitalization rule precluding the deductibility of certain interest payments indirectly leads to taxation (by assessment) in the source state. Unless the thin capitalization rule can be considered as an authorized anti-abuse measure, it will in our view constitute an infringement to the IRD.
Hybrid instruments
Member states are not obliged to grant the application of the IRD benefits to income generated by certain hybrid instruments, that is, profit-participation certificates, debt instruments under which payments can be regarded as profit distributions, convertible bonds and perpetual bonds.
Transitional measures
For budgetary reasons, certain countries (net importers of capital and technologies) may progressively reduce the tax levied at source over a transitional period (see below).
Proposed amendments
On December 30 2003, the Commission introduced a proposal amending the scope ratione personae of the IRD.
Extension of the list of companies qualifying under the IRD
The list of companies (annex to the IRD) will be broadened. Two obvious examples are the two specific EU legal company forms:the European company (Societas Europaea), and the European cooperative company.
But also other legal forms of various countries have been added to the list, such as, for example, the French sociétés par actions simplifiées (SAS). As the latter is a common company form in France, there was no reason to exclude it from the benefit of the IRD.
The list will further have to be amended to include the company forms of the 10 accession countries on May 1 2004.
Beneficiary not effectively subject to tax on interest and royalty income
The amending proposal contains an anti-abuse provision:in the case of an EU company/PE not being effectively subject to tax on the interest or royalty payments, the benefit of the IRD will not be applicable, meaning that the source state of the income may levy tax on such interest or royalties.
Is this provision only applicable to fully exempt income, or can a partial/major exemption jeopardize the benefit from the IRD? As this constitutes an exception to the IRD provisions, it should be interpreted in a limitative way. Hence, only fully exempt interest or royalty income is in our view covered by this exception.
Date for amendments
In case the IRD is amended in accordance with this proposal, the changes should be implemented by December 31 2004 (May 1 2004 for accession state legal forms).
Belgium's experience of transposition
The specific case of transposition in Belgium illustrates how local transposition may still be different from the (generic) IRD provisions.
Scope ratione materiae
The exemption of WHT applies to income defined as follows:
interest: income either from bonds, cash certificates or other, similar instruments, or from receivables or loans, except for capitalization bonds and zero-bonds;
royalties: income from the rental, hire, use or licensing of moveable property.
The Belgian transposition excludes capitalization bonds and zero-bonds from the benefit of the IRD, although the IRD does not provide such this exclusion. Therefore, a taxpayer could in our view invoke the direct effect of the IRD, as we doubt that the exclusion can be considered as an authorized anti-abuse clause.
Scope ratione materiae
Associated companies - the holding condition
"Associated companies" are two EU companies that meet following conditions:
either, one of the two EU companies has a direct or indirect holding of at least 25% in the capital of the other one for an uninterrupted period of at least one year;
or a third EU company has a direct or indirect holding of at least 25% in the capital of each of the companies for an uninterrupted period of at least one year
Unlike the IRD, Belgian law stipulates explicitly that the common parent must be located in the EU.
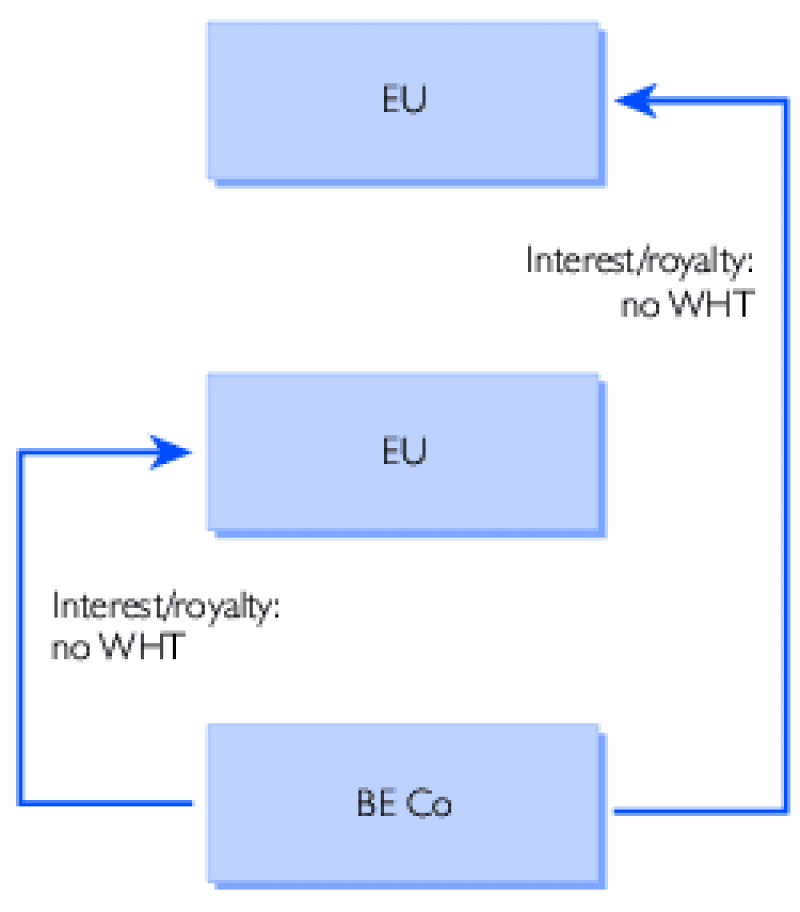
Furthermore, Belgium has broadened the scope of exemption to payments between indirectly related companies (in line with the initial draft directive): the exemption will be applied in many more cases than those foreseen in the IRD (see diagram 4).
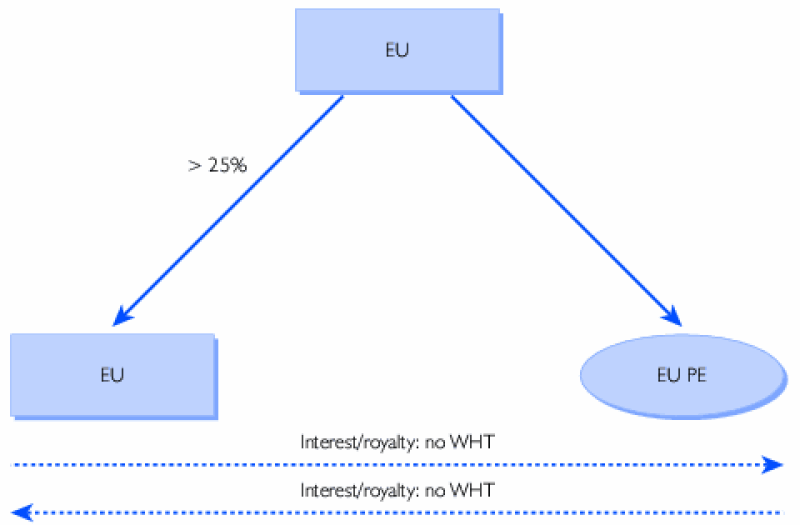
Interest and royalties are exempted from WHT where the beneficiary is identified as a company of a member state or a Belgian resident company: the benefit of the IRD is also applied for pure Belgian payment, and regardless of the legal form of the Belgian beneficiary, provided of course all other conditions are met.
Diagram 3: Associated companies (3) |
|
Diagram 4: Belgian case |
|
Beneficiary v beneficial owner
The Belgian transposition decree refers to the beneficiary of the income (not the beneficial owner as mentioned in the IRD). The scope of the notion beneficial owner v beneficiary is often subject to discussions in Belgium, as the Belgian tax authorities tend to apply the concept of beneficial owner even in cases where not explicitly mentioned in, for example, a tax treaty. Therefore, although the Belgian transposition decree has a broader wording (beneficiary) than the IRD (beneficial owner), it should be monitored how the Belgian authorities will apply the WHT exemption in case of mere conduit beneficiaries, in practice.
Holding condition = retention period
The WHT exemption is subject to the holding condition being fulfilled for one year, without requiring that this minimum holding period is already met at the moment of payment/attribution of the interest or royalties.
Hybrid instruments - excessive payments
Belgium has not made use of the option to exclude income from hybrid instruments from the benefit of the IRD. Furthermore, there is no explicit exclusion of excessive interest and royalties. However, Belgian domestic tax law already contains provisions preventing the deductibility of (or even taxing) excessive payments.
Effective date
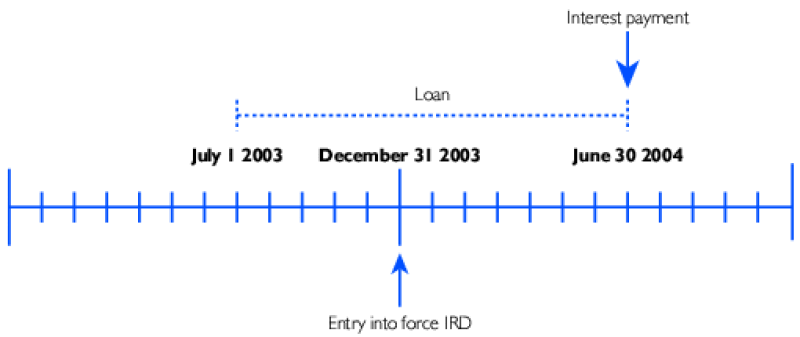
The exemption applies to income paid/attributed on or after January 1 2004 and where such income relates to a period after December 31 2003. This means that interest generated before but paid after January 1 2004 cannot benefit from this exemption: in the example of diagram 5, only the interest relating to the period as from January 1 2004 until June 30 2004 will benefit from the exemption; the pro rata interest relating to the period from July 1 2003 until December 31 2003 will be subject to WHT (unless other exemptions would apply).
In our view, this limitation goes beyond what is foreseen by the IRD, and, therefore, the WHT would not be in line with the IRD.
Diagram 5: Income generated before but paid after implementation |
|
Not the same
As can be seen, on some aspects, Belgium goes beyond the IRD provisions:
indirect holdings;
one-year holding period (retention period); and
exemption for hybrid instruments as well.
However, some specific measures are stricter than the IRD and in our view therefore not fully EU compliant:
interest on capitalization and zero-bonds in principle always remains subject to Belgian WHT; and
non application for interest/royalties generated prior to (but paid after) January 1 2004
The future
The member states still need to do some work before effective and full transposition of the IRD is a reality. In case of delay or inaccuracy in transposition, owing to the clarity of the IRD's terms, taxpayers will nonetheless be able to apply it because of its direct effect. Following the ECJ's Bachmann decision, it is generally admitted that a European directive is of direct effect in internal law where the terms are unconditional in nature and sufficiently precise. This will be the case of the IRD.
By December 31 2006, the Commission will, in any event, have to report to the Council on the application of the IRD with a view, among others, to extend the benefit of the IRD to other forms of doing business.
The state of implementation |
The situation in the 25 present and acceding member states as on April 15 2004 is summarized in the table below. Countries having transposed the IRD As of April 15 2004, only eight of the current member states (Austria, Belgium, Denmark, Finland, France, Ireland, the Netherlands and Spain) and one of the acceding member states (Czech Republic) have transposed the IRD into domestic law. Countries that (will) benefit from transition periods Some current member states will benefit from a transition period:
These exceptions may not give rise to double taxation of interest or royalties. In case of double taxation, the member state of residence of the beneficiary has to grant a tax credit which may not exceed the lower of, on the one hand, the tax retained at source or, on the other hand, the part of the tax that is due in the beneficiary's state of residence on the amount of the interest or royalties as computed before the tax credit is given (gross amount). Some acceding member states have requested a transition period. On April 1 2004, the Commission introduced a proposal COM (2003) 243 in order to insert transitional rules:
The proposal explicitly mentions that any lower tax rate laid down in double tax treaties between the above-mentioned countries and the other member states will apply. Countries that do not have to (completely) implement the IRD Domestic tax law already (conditionally in some cases) exempts interest and royalty payments from WHT in Luxembourg, the Netherlands, Cyprus, Hungary and Malta. At first sight, these member states should not have to take any action to transpose the IRD into their respective domestic laws. Nevertheless, in absence of a formal transposition, whenever the domestic tax law of these countries would be more restrictive than the IRD (for example, thin capitalization rules, strict conditions or any other form of taxation by assessment), the direct effect of the IRD could in our view be invoked. Associated companies - the holding condition Only Belgium and Slovenia take account of indirect holdings in determining the holding threshold. The holding period condition Slovenia and Lithuania intends to apply a waiting period (as opposed to a retention period). Finland, Sweden and UK do not require any holding period. |
Member state |
Current domestic WHT on cross-border payments* |
IRD implementation |
Indirect Participation |
Holding period |
|
Duration |
To be met upon attribution / payment? |
||||
Austria |
Interest : no WHT Royalties : 20% WHT |
Applicable as from January 1 2004 |
No |
1 year |
Yes (but claim back possible) |
Belgium |
Interest: 15% WHT Royalties: 15% WHT |
Applicable as from January 1 2004 |
Yes |
1 year |
No |
Cyprus |
Interest : no WHT Royalties : no WHT |
Not implemented yet |
N/A |
N/A |
N/A |
Czech Republic |
Interest : 15% WHT Royalties : 25% WHT |
Applicable as from May 1 2004. Proposal: six years transitional period for royalties (max 10%) |
No |
24 months |
No |
Denmark |
Interest : no WHT Royalties : 0% WHT (but draft bill of law) |
Applicable as from January 1 2004 |
No |
1 year |
Still unclear |
Estonia |
Interest : 26% WHT Royalties : 15% WHT |
Draft legislation under negotiation |
No further details available |
||
Finland |
Interest : no WHT Royalties : 29% WHT |
Applicable as from January 1 2004 |
No |
No holding period required |
|
France |
Interest : 0/15% WHT Royalties : 33.33% WHT |
Applicable as from January 1 2004 |
No |
2 years |
No |
Germany |
Interest : 0/30% WHT Royalties : 0/20% WHT |
Draft legislation |
No further details available |
||
Greece |
Interest : 15/20% WHT Royalties : 0/20% WHT |
Transitional period of eight years. First four years max 10% WHT, last four years max 5% |
N/A |
N/A |
N/A |
Hungary |
Interest : no WHT Royalties : no WHT |
Not implemented as such but WHT on interest and royalties abolished |
N/A |
N/A |
N/A |
Ireland |
Interest : 20% WHT Royalties : 20% WHT |
Applicable as from January 1 2004 |
No |
2 years |
No |
Italy |
Interest : 12.5% WHT Royalties : 30% WHT (on 75% of the gross amount) |
Standstill |
No further details available |
||
Latvia |
Interest : 0/10% WHT Royalties : 5/15% WHT |
Not implemented. Proposal: six years transitional period. First four years: max 10% WHT. Last two years: max 5% WHT. |
No further details available |
||
Lithuania |
Interest : 10% WHT Royalties : 10% WHT |
Draft law in progress. Proposal: six years transitional period. First four years: max 10% wht. Last two years: max 5% WHT. |
No |
2 years |
Yes |
Luxembourg |
Interest : no WHT Royalties : 10% WHT (new draft bill: no WHT) |
Draft bill issued |
N/A |
N/A |
N/A |
Malta |
Interest : no WHT Royalties : no WHT |
Standstill |
N/A |
N/A |
N/A |
The Netherlands |
Interest : no WHT Royalties : no WHT |
Applicable as from January 1 2004 |
N/A |
N/A |
N/A |
Poland |
Interest : 20% WHT Royalties : 20% WHT |
Not implemented. Proposal: six years transitional period for royalties only: max 10% WHT. |
No further details available |
||
Portugal |
Interest : 20% WHT Royalties : 15% WHT |
To be implemented before end 2004 ? 8 year transition period. First 4 years: max 10% WHT. Last 4 years max 5% WHT. |
No further details available |
||
Slovakia |
Interest : 19% WHT Royalties : 19% WHT |
Not implemented. Proposal: 2 years transition period for royalties only |
No further details available |
||
Slovenia |
Interest : no WHT Royalties : no WHT |
Draft legislation |
Yes |
24 months |
Yes |
Spain |
Interest : 15% WHT Royalties : 25% WHT |
Implemented. 6 year transition period for royalties: max 10% WHT. |
No |
1 year |
No |
Sweden |
Interest : no WHT Royalties : no WHT |
Draft legislation |
No |
No holding period required |
|
United Kingdom |
Interest : 20% WHT Royalties : 22% WHT |
Draft legislation |
No |
No holding period required |
|
* These are the nominal rates and do not take into account specific exemptions, reductions under either domestic tax law or tax treaties. |
|||||
Philippe de Clippele (philippe.de.clippele@pwc.be), Benoît Verschueren (benoit.verschueren@pwc.be).





