
Over the last 20 years, and more particularly the last decade, many non-Chinese multinational enterprises (MNE) have increased the amount and complexity of intercompany transactions with Chinese affiliates. Not only are tangible goods involved, as may have been primarily the case earlier in the development of China, but also transactions related to intercompany services and intangibles. With increasing attention being paid by Chinese tax authorities to these deals, and with the increasing complexity of issues and transactions, MNEs can expect to work harder to balance the expectations of tax authorities inside and outside of China.
China's tax authorities have moved to strengthen transfer pricing-compliance enforcement efforts in recent years, and non-Chinese MNEs therefore should prepare for potential transfer pricing-related audits in China, while considering the possibility of adjustment to the parent company's assessments by tax authorities in other jurisdictions. A number of procedural remedies exist for addressing potential adjustments in China, including negotiation to settlement with the field team, domestic appeals in China, pursuing competent authority relief or considering a unilateral or bilateral advance pricing arrangement (APA).
Among these domestic Chinese procedural alternatives, the APA mechanism is perhaps the most viable option in many situations for non-Chinese MNEs to achieve certainty of tax treatments and to resolve real or potential transfer pricing disputes. Involvement of other treaty partners through the competent authority or bilateral APA process may help eliminate the potential for economic double taxation.
History and status of the APA in China
The APA concept was first introduced in formal transfer pricing regulations (Guoshuifa [1998] No 59) in 1998. The first unilateral APA in China was concluded in 1998 between a Chinese taxpayer and a local tax authority. Since then, more than 100 APAs have been concluded, all of which are unilateral, with the exception of one bilateral APA (BAPA) between China and Japan in 2005.
China's State Administration of Taxation (SAT) processed 18 unilateral APAs in 2005, and is processing 10 bilateral APA applications, involving Japan, South Korea and the US.
In September 2004, the SAT issued a set of formal APA rules in Guoshuifa [2004] No. 118 (the APA rules).
The APA rules provide comprehensive guidance on the procedures for concluding an APA, from pre-filing, to the signing of the APA, and the responsibilities of the taxpayer and tax authorities during the term of the APA.
The APA rules cover a wide variety of transactions such as the sale and use of tangible assets, the transfer and use of intangible assets, the provision of services, and loan transactions.
According to the APA rules, the term of an APA may range from two years to four years starting from the year after the filing of the formal APA application. The term of the APA can be extended to a maximum of five years. No rollback to years before the application year is allowed.
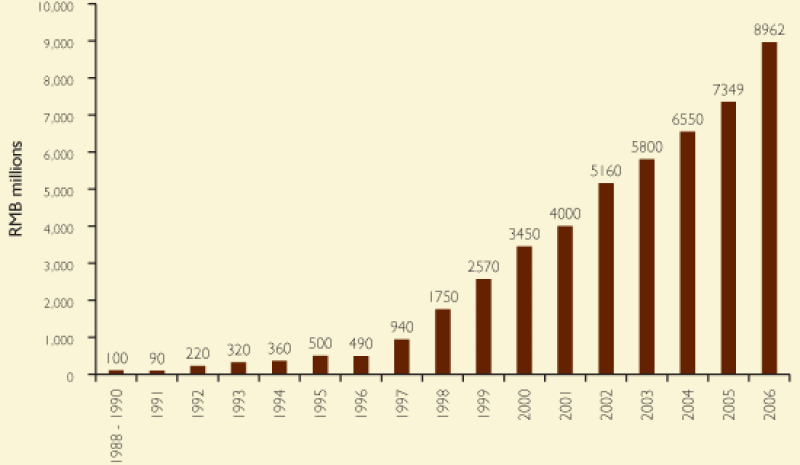
Diagram 1: Adjustments to taxable income |
|
APA procedures
The APA applications are primarily processed by the local governing tax authorities who are responsible for evaluating the APA applications and concluding the APA. The APA procedures involve six steps, and generally may take at least a year to complete. These steps include:
pre-filing meeting
formal application
examination and evaluation
negotiation
signing the APA
execution and monitoring.
The SAT's role in APAs
The APA rules specifically refer to the SAT's involvement in the coordination and supervision of the APA process when it involves:
three or more provincial cities
significant related-party transactions of at least RMB10 million ($1.207 million)
a bilateral or multilateral APA.
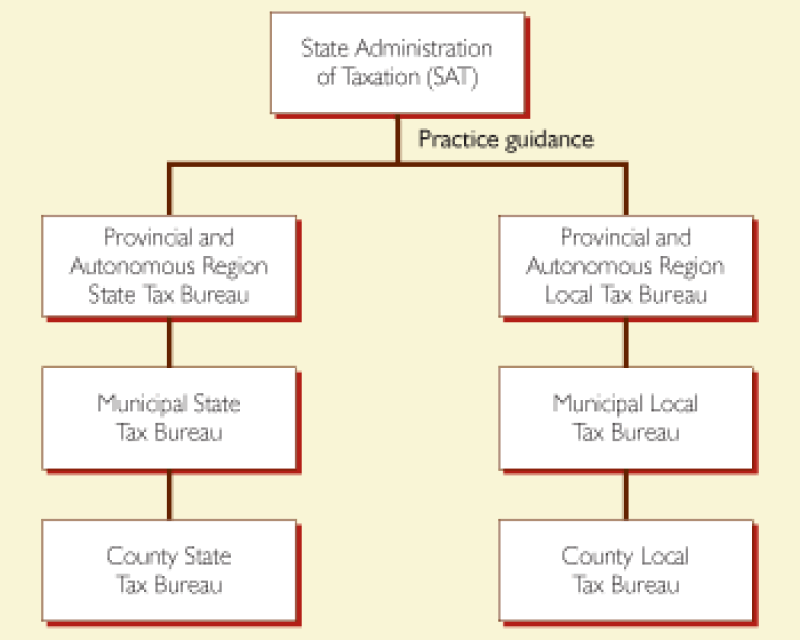
Diagram 2: How the Chinese tax authorities are organised |
|
The APA application generally is processed by the local governing tax authority where the taxpayer is located. Under the current tax administration system in China, the municipal tax authority may need to report to its provincial tax authority regarding the APA application. As a result, three layers of tax authorities (that is, SAT, provincial and municipal) may be involved in the APA process.
In the circular Guoshuihan [2005] No. 1172, the SAT reinforced its goal to centralise control of APA approvals. According to SAT officials, the centralised approval requirement is viewed not only as an enhancement to the technical and practical quality of the local tax authority's work, but also as a vehicle for bringing changes to transfer pricing analysis by the local tax authorities.
Under Chinese APA rules, if taxpayers apply for APAs involving several domestic entities located in two or more provincial cities, the SAT must be involved and coordinate with the different tax authorities in the intra-China APA applications. However, the SAT may not take great interest in the intra-China APAs due to the perceived lack of benefit to the SAT. The intra-China APAs probably would not increase China's tax revenue, but the SAT may risk alienating a local tax authority during the process.
Bilateral and multilateral APAs
The APA rules mainly cover unilateral APAs, but also cover bilateral and multilateral APAs. A unilateral APA is an arrangement between a taxpayer and the Chinese tax authorities, whereas a bilateral or multilateral APA also involves the competent authorities of one or more treaty partners. For bilateral or multilateral APAs, the APA rules are augmented by those for mutual agreement procedures (MAP).
As the SAT has limited resources to process APA cases, it intends to be more selective in accepting bilateral APA cases. For large industry MNEs from strategic trading partners, the SAT appears to welcome opportunities to secure bilateral APAs. Another interesting development in selecting bilateral APA candidates is that the SAT entertains APA applications for situations that may present themselves under hypothetical circumstances in the future.
Motivation of tax authorities vs taxpayers
Before the issuance of the APA Rules, early APAs in China more closely resembled advance rulings rather than formal APAs. Now, however, Circular 1172 requires all local tax authorities to comply with the nation's APA rules in accepting APA applications. Under the Chinese tax administration system, there are at least three layers of tax authorities, including municipal tax authorities, provincial tax authorities and the SAT. As required under the APA rules, all APA applications have to be filed and processed by local tax authorities at the municipal levels. The municipal tax authorities may report the APA applications to provincial tax authorities if the municipal tax officials do not have sufficient experience of APAs. The SAT may be more involved in the details of the APA process if the APA applications meet certain criteria. As each tax authority has its own jurisdiction, one cannot assume that all tax authorities will have the same motivations when considering or processing an APA application.
For example, as the SAT has extremely limited resources to be involved directly in evaluating APA applications, the SAT has to coordinate with the municipal or provincial tax authorities. One cannot assume that a "top-down" approach will achieve quick results in APA applications. Taxpayers should follow the APA rules procedures and respond to issues raised by municipal or provincial tax authorities before approaching the SAT.
As a result, it is very important to monitor closely the interactions among the different layers of tax authorities when applying for APAs in China. In particular, for an APA application involving different entities located in different tax jurisdictions in China, if the application may cause potential tax revenue allocation issues among different tax jurisdictions, the municipal or provincial tax authorities may be reluctant to process the APA application in good time.
|
|
Steven Tseng and Julian Hong |
From the taxpayer's perspective, one cannot assume that the local management of Chinese subsidiaries necessarily have the same motivations of the parent company when considering an APA. The parent company of an MNE generally prefers an APA that can assist to mitigate potential transfer pricing risks, achieve certainty of tax treatments and comply with global transfer pricing policies. However, local management may not want to "rock the boat," as they may consider an APA application to be a potential audit trigger for other tax issues.
If the local subsidiary has a Chinese joint venture (JV) partner, it is crucial to align with the expectations of the JV partner when considering an APA. If an APA is to cover related-party transactions that may have potential implications for the interest of the JV partner, MNEs should consider this and plan accordingly.
Analysis
As the APA application will be reviewed and debated among tax officials in China (in the case of a unilateral APA) or in other countries (in the case of a bilateral or multilateral APA), the application should be completed based on sound theoretical grounds and cover important issues before submission. With increasing sophistication in transfer pricing technical skills, Chinese tax officials can be expected to raise many questions on the proposed transfer pricing methods and comparable information discussed in the APA application. If an application does not address important issues in advance, it is likely that tax officials may lose focus on the core issues, and the evaluation of that APA application may take longer. For example, if the covered transaction is only a small portion of total related-party transactions, the taxpayers should be prepared to explain the transactions that are not covered.
Negotiations
Part of any successful negotiation is to understand and meet the expectations of all parties. To meet expectations, taxpayers should put forward a well-prepared APA application with a realistic proposal, and should be prepared to be flexible for possible compromises. As the negotiation process is interactive and dynamic, the taxpayer's credibility may be undermined if the taxpayer negotiates an APA with a preconceived result.
Under the APA rules, taxpayers are required to provide written documentation in the pre-filing meetings on the proposed transfer pricing method. In the pre-filing meeting, the taxpayer must also provide functional and risk analyses, an economic analysis, as well as critical assumptions and other relevant information regarding the related-party transaction(s). In essence, the taxpayers must submit a draft APA application at the pre-filing stage. Therefore, the negotiation process effectively commences immediately when the taxpayers attend the pre-filing meeting. Accordingly, proactively determining the appropriate negotiation methods early on can be critical when applying for APAs in China.
Confidentiality
Taxpayers probably will submit substantial documentation and other information during the course of applying for APAs and should therefore carefully consider these disclosure requirements. Both the tax authority and taxpayer are obligated to maintain the confidentiality of the information provided during the APA application process.
Compliance and renewal
If taxpayers have successfully concluded APAs with China's tax officials, taxpayers should not assume a renewal of the existing APA is an easy task. Experience confirms that Chinese tax officials may request that taxpayers apply new comparable information or analysis in APA renewals. For example, after the SAT recently concluded several transfer pricing audits on certain industries, tax officials requested a MNE to amend its analysis of comparable information in the APA renewal application. Taxpayers should monitor transfer pricing enforcement developments and carefully assess the feasibility of an APA renewal before submission of an application.
|
|
Fred Johnson and Steve Harris |
APA applications involving royalty transactions
Regulatory issues
For an APA involving royalty payments, there are a number of regulatory issues to consider. Under current regulations, if the royalty payment relates to technology usage, the taxpayer is required to register a technology transfer contract with the authority responsible (that is, the Ministry of Commerce). However, the regulatory authority in charge may not approve a contract registration imposing variable royalties or a high royalty rate.
Extra tax implications
If a Chinese entity is to pay royalties to a recipient outside of China, there may be other tax implications, including potential customs charges, and business and withholding taxes. If a royalty payment relates to advanced technology transfers, the taxpayer may be allowed to apply for a business tax exemption. However, if a taxpayer cannot partition the royalty payments between trademarks and technology, or if adequate documentation is not provided, China's tax authorities may deem the entire royalty as trademark-related and subject it to a business tax.
Competent authority
Although the SAT has limited exposure to competent authority (CA) negotiations and minimal experience in negotiating bilateral APAs, it has adopted the generally accepted practices of other developed countries, including the mutual agreement procedure article of China's tax treaties. The SAT issued Guoshuifa [2005] No. 115 (Circular 115) to confirm that China will use the mutual agreement procedure of its tax treaties to resolve transfer pricing disputes. In the SAT, the international taxation department is responsible for CA negotiations.
Under Circular 115, taxpayers considering CA relief are obliged to file a written application with their local tax authorities within three years after receiving a tax assessment notice. Among other information, the application is to include the opinion and rationale of the adjusting tax authority (if other than China) and the taxpayer, and the contracting state.
Chinese CA procedures should be integrated with APA procedures when a bilateral or multilateral APA is under consideration.
Coordination involving China tax treaty partners
In the last few years, China has stepped up efforts to integrate its approach to APA and competent authority practices with those of its treaty partners. Particularly important to China's continued maturation as a full member of the global bilateral APA community is its relationship with its counterparts in countries with major economic power, such as the US, Japan, South Korea and the UK.
While case-specific details of China's interaction with its treaty partners are not disclosed publicly, experience suggests that bilateral APA activity by the SAT has been stepped-up. The SAT has embarked on a mission to establish its bona fides as an adherent to arm's-length principles through the bilateral APA mechanism. Considering the relatively recent release of its APA-related guidelines in 2004 and 2005, the SAT is just beginning to ramp up its efforts. From recent discussions with the SAT, it appears it wants to establish policy on how to treat various issues affecting large MNEs and industries operating in China through the bilateral APA mechanism. This presents both challenges and opportunities for MNEs.
APA and competent authority implications for MNEs
The ability to use an effective and efficient APA programme is an essential part of any MNE's overall strategy to manage its transfer pricing risks. The fact that China is actively developing a vibrant APA programme should be a welcome sign for MNEs doing business in China. An APA is often a better alternative to the traditional transfer pricing examination.
As Chinese tax officials continue to step-up their enforcement efforts on transfer pricing issues, MNEs should consider APAs seriously. In China, the decision whether to choose an APA over the "file and wait for audit" approach should follow a similar process to that already undertaken by MNEs in other countries. One of the keys to this decision is the MNE's confidence in the tax authority's commitment to the APA process.
China has clearly modeled the procedures and parameters of its APA programme after those already established in other countries. The country's APA submission requirements as well as the evaluation process should be familiar to MNEs who have experience with APAs in other countries. These similarities should make MNEs more comfortable with what to expect from Chinese tax officials. If China's APA programme is able to deliver consistent principled resolutions on MNEs' transfer pricing issues, then MNEs should consider the APA option.
In addition, as China begins to expand its bilateral APA programme, APAs will become more attractive to MNEs who prefer upfront resolution on both sides of their intercompany transactions. China has limited bilateral APA experience to date. It can be expected that it will build its capabilities on a solid procedural foundation and fine-tune its approach over time. It can also be expected that, as China formalises the role of its international tax cadre in Beijing, a more focused and centralised approach to the selection of appropriate cases for APA and competent authority consideration will ensue.
APA procedures |
Pre-filing meeting Under the APA rules, the pre-filing meeting is a required first step in the APA application procedure and the meeting must be conducted on a named basis. Anonymous pre-filing conferences are not allowed. Formal application After receiving a written consent of the local tax authority, the taxpayer is required to file a formal APA application within three months. The formal APA application should include at least the following:
Examination and evaluation The local tax authority's examination and evaluation will focus on six major areas:
Both the tax authority and taxpayer are obligated to maintain the confidentiality of the information provided during the APA application process. When an APA cannot be reached, the tax authorities should return to the taxpayer the information and documents provided. In addition, any non-factual information collected during the APA application process (for example, suggestions or judgements) cannot be used by the tax authority in any subsequent transfer-pricing audit. Negotiation After completion of the examination and evaluation process, the governing tax authority will negotiate issues in the aforementioned six major areas with the taxpayer. If both the tax authority and the taxpayer can reach agreement, both parties may then draft the APA. Signing the APA Generally, a formal APA can be signed within 30 days after both the taxpayer and the tax authority reach an agreement on the draft APA. The APA is not automatically renewable. The taxpayer is required to apply for a renewal with the local tax authority at least 90 days before the APA expires. When applying for a renewal, the taxpayer must provide reliable evidence that the facts and circumstances stated in the existing APA have not materially changed. The tax authorities should complete the examination and evaluation process and prepare a draft APA within 60 days after receiving the taxpayer's renewal request. Execution and monitoring After the APA has been finalised, the taxpayer is required to submit an annual report with the governing tax authority within four months after the end of its taxable year. In addition, the taxpayer is expected to report to the tax authorities in charge any substantial change(s) affecting the APA, within 15 days following the date on which the change occurred. |
Steven Tseng (steven.tseng@kpmg.com.cn), partner-in-charge of KPMG's global transfer pricing services in China and Hong Kong, based in Shanghai; Julian Hong (julian.hong@kpmg.com.cn), senior manager, KPMG Huazhen's global transfer pricing services practice, Shanghai; Steven Harris (sdharris@kpmg.com), principal, KPMG LLP, and practice leader of KPMG's global transfer pricing resolution network, based in New York and Fred Johnson (fcjohnson@kpmg.com), senior manager KPMG LLP's global transfer pricing services practice, Mountain View







