
With the goal of strengthening the country's international competitiveness, Japan's Diet authorized an amendment of its Commercial Code in 2000. This amendment introduced new rules covering the treatment of corporate divisions in Japan. In connection with this amendment, the Tax Code was modified as well.
Specifically, the tax reforms effective from March 31 2001, change the Japanese corporate tax treatment of reorganizations. They replace the current merger, investment in-kind and post-establishment transfer ( jigo setsuritsu) rules and introduce new rules relating to corporate divisions.
1. CORPORATE TAX
1.1. Taxable / non-taxable reorganizations
One Commercial Code amendment of particular significance to reorganizations is the introduction of the concept of corporate divisions in reorganizations (effective April 1 2001). In terms of economic substance, corporate divisions are similar to investments in-kind and post-establishment transfers. Mergers, however, represent the opposite type of reorganization. In association with the change in the Commercial Code, the tax rules were changed so that the regimes remain consistent.
(1) Judgement of taxability of reorganizations under the former tax legislation and under the new tax legislation are compared below:
Under the new tax legislation in principle, a reorganization shall be taxed. Exemptions from tax will only be granted to (i) reorganizations within a group (a "group reorganization"), or (ii) reorganizations for the purposes of a cooperative business, which meets certain qualifications.
Previous approach |
From April 1, 2001 |
|
Merger |
|
|
Divisions |
No provision |
|
Investment in Kind |
|
|
Post-establishment transfer |
|
|
Note: Exchanges or transfers of shares are excluded from reorganization as prescribed above. |
||
(2) Corporate tax treatment of reorganization under the former & new tax legislation
Under the new tax law assets and liabilities are to be assumed at book value if the requirements for qualification are met, regardless of how they are processed for accounting purposes.
Previous approach |
From April 1, 2001 |
Remarks |
|
Merger |
|
|
|
If the merger meets the requirements for qualification
(Unrealized gains and unrealized losses are to be assumed as is)
|
§62-2 (1) The difference between accounting and taxes shall be added to capital reserves (§2,17 and 8 of new law) Parenthesis of §24 (1) of new law. The merging ratio is not a factor in determining taxation. |
||
If requirements for qualification are not met
|
§62 (1) of new law §24 (1) of new law |
||
Division |
No Provision |
|
§62-2 (1)
Parenthesis of §24 (1) of new law §62 (1) of new law §24 (1) of new law |
If requirements for qualification are met
|
|||
If requirements for qualification are not met
|
|||
Investment in kind |
|
|
§62-4 (1) of the New Law
|
Post-establishment transfer |
|
|
§62-5 (1) of new law |
Notes: The ability to choose taxable or non-taxable treatment through accounting will no longer exist. If the requirements for qualification are met, the capital gains or losses cannot be realized even if the company wishes to do so. Consequently there is no longer any option to have only an appropriate amount taxed within the range of the market value. If the reorganization is a qualifying reorganization, neither unrealized gains or unrealized losses will be recognized for the purpose of taxation. |
|||
1.2. Qualifying reorganizations / requirements
Requirements for qualifying reorganization
In order to be recognized as a Qualifying reorganization, and thus receive favourable tax treatment, the reorganisation itself must meet certain requirements. These requirements are summarized below.
Taxes Deferred |
|||
Group Reorganization |
|||
Relationship of 100% Ownership |
More than 50% but less than 100% |
Joint Enterprise |
|
Merger (1) Qualifying Merger (§2(xii-viii) of new law) |
No requirement of continuing the business (No cash or the like as consideration) |
(no cash or the like as consideration) |
and * Requirement of related business * Requirement of size (*2) * Requirement of continuous ownership of shares, etc. (no cash or the like as consideration) |
Corporate Division (*1, *3) Qualifying Division (§2(xii-xii) of new law) |
|||
Investment in Kind Qualifing Investment in Kind (§2(xii-xiv) of new law) |
|||
Post-establishment transfer (§2(xii-xv) of new law) |
Qualifying Post Establishment Transfer
|
||
If a qualifying reorganization, assets & liabilities will be transferred at tax basis. If a non-qualifying reorganization, assets & liabilities will be transferred at fair market value, and the difference will be recognized at its capital reserve. |
|||
*1. Under a merger or corporate division the business is by law to be continued. The reorganization will no longer meet the requirements for qualification if the business is abolished immediately after the reorganization takes place.
*2. In general whichever of sales, number of employees and other similar matters must be at a ratio of within 1:5 (or participation in management of both companies in exchange for the size requirement, at the managing director level or above)
*3. A non-proportional type corporate division ( Hianbun bunkatsu-gata bunkatsu) is a non-qualifying reorganization.
*4. Under the Commercial Code, in the event of a merger, all assets of the merged company are assumed; this requirement is thus not specified under the tax law.
1.3. Net operating loss carryforwards
Under the previous law, the net operating loss (NOL) carryforwards of the transferor company could not be carried over to the transferee company.
If a merger (or corporate division followed by liquidation of transferor ( shometsu bunkatsu)) satisfies the requirements for a qualifying reorganization, the NOLs of the merged or transferor company can be used by the merging or transferee company. However, if the joint business operations requirements are not satisfied, NOLs that were incurred before the companies became group companies (ie companies with a shareholding relationship in excess of 50%) would be lost, unless the net unrealised gains at the time the companies became group companies exceeded said NOLs. (See the flow chart 1.)
1.4. Limitations on utilization of capital losses from transfer of assets
If qualifying reorganizations (mergers, divisions, investments-in-kind, post-establishment transfers) between group companies take place without satisfying the joint business operations requirements, any loss from the sale of assets (acquired before the companies became group companies), with exceptional assets, would not be deductible for tax purposes. This limitation does not apply to losses from assets that are sold more than five years after the date when the companies became group companies or more than three years after the date of reorganization, whichever is earlier. (See the flow chart 2.)
2. TAXATION OF THE SHAREHOLDERS OF THE TRANSFEROR COMPANY
If the shareholders (individuals and companies) of the transferor company receive only shares of the transferee corporation in connection with a qualifying reorganization, they do not recognize constructive dividend and capital gains/losses for Japanese tax purposes. In the case of non-qualifying reorganizations, however, the shareholders (individuals and companies) of the transferor company will in principle recognize constructive dividend income. In simple terms, the amount of such constructive dividend income would correspond to the distributable retained earnings of the transferor company. Corporate shareholders may generally exclude constructive dividend income from taxable income, but individual shareholders may not. If any cash distribution is made in non-qualifying reorganization, capital gain or loss also need to be recognized in addition to constructive dividend.
3. ANTI-ABUSE PROVISION
If the tax authorities conclude that a reorganisation results in an unjustifiable reduction in the tax burden, they have the power to reassess taxable income.
4. REGISTRATION AND LICENSE TAX
The Registration and License Tax is a national tax levied when official records and documents are registered in connection with the acquisition, creation, transfer, alteration, or other modification of rights.
When a corporate division results in a capital increase (ie due to the transfer of assets from the transferor company), the Registration and License Tax is imposed on the transferee corporation at a rate of 0.15% of the capital increase. However, tax at a rate of 0.7% (instead of 0.15%) applies to the portion by which the increase in the capital of the transferee company exceeds the decrease in the capital of the transferor company prior to the corporate division.
Note: The above is the same for merger, but in case of investment in kind and post-establishment transfer 0.7% of increased capital applies.
A special reduced rate of 0.6% would apply to transfers of land or buildings in connection with a corporate division for five years from the effective date of the reform package (compared to the regular rate of 5%).
Note: In case of merger 0.6% applies, and other reorganization 5% will be applied.
5. CONSUMPTION TAX
The transfer of assets in a merger or in a division is not considered to be a taxable event for Japanese consumption tax purposes. Therefore, such transfers are not subject to consumption tax regardless of whether the reorganization is qualifying or non-qualifying for corporate tax purposes.
Note: In case of investment in kind and post-establishment transfer consumption tax is imposed at a rate of 5%.
6. CONSOLIDATED TAX RETURN
Although the tax reform package does not contain specific provisions regarding consolidated tax returns, it sets April 1 2002 as the target date for the introduction of the consolidated tax return regime.
CONCLUSION
The recently introduced tax laws can significantly reduce the tax burden of the entities undertaking a reorganization. In the case of certain types of merger, however, the tax burden may be greater than it would have been under the previous law. If a merger or division is structured correctly, the accompanying tax burden may be relieved. As such, for any Japanese corporation, a thorough knowledge of the new tax reforms is essential.
CASE STUDY
Case 1 / NOL utilization in a merger
Assumptions:
Both Co A and Co B are Japanese corporations.
The fiscal year of each company is a calendar year.
Co A has owned Co B since 1999 (100%), the year they became group companies.
Co A merges Co B in 2002. (Co A is the merging company and Co B is the merged company.)
No cash or the like as consideration upon the merger.
The merger does not satisfy the deemed joint enterprise conditions.
Co A does not have net operating losses carry-forward, for tax purposes.
Co B has net operating losses carry-forward for tax purposes.
The amounts of these losses appear below:
FY 1998 – JPY 100M, FY1999 – JPY 90M, FY 2000 – 80M, FY2001 – JPY 70M
Tax consequences of the NOL after the merger:
The above merger meets the requirements for qualifying reorganization.
The NOL transferred from Co. B to Co.A is JPY 240M (JPY 90M+80M+70M).
The NOL before group company that cannot be transferred from Co. B to Co. A is JPY 100M.
Case 2 / The price of transfer assets in a merger
Assumptions:
Co A and Co B are Japanese corporations.
Co A owns 100% of Co B's share at JPY100M.
These shares are cancelled upon the subsequent merger.
Co A merges Co B. (Co A is the merging company and Co B the merged company.)
No cash or the like as consideration upon the merger.
The book value of the transferred assets is JPY50M.
Journal entry by Co A, for tax purposes:
The merger above meets the requirements for qualifying reorginization.
(Dr) Assets 50M (Cr) Co B share 100M
Capital reserve 50M
(ie, Step up of goodwill is no longer allowed.)
Attachment 1
RESTRICTIONS ON USE OF LOSSES UNDER A QUALIFYING MERGER (FLOWCHART 1)
(1) Basic Concept
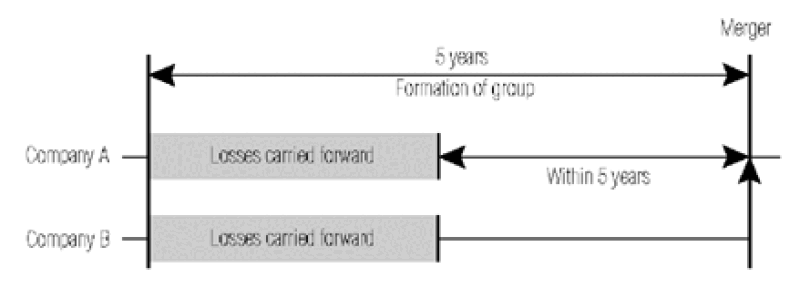
1. Losses carried forward of the merged corporation can be assumed under a qualifying merger (section 57(2) of the Law)
2. If the merger is a qualifying merger under the requirements for a group reorganization, in principle losses carried forward which were generated prior to forming the group cannot be used if less than five years have passed since the forming of the group (section 57(3) and (6) of the Law)
3. The intention is to prevent mergers which are designed for the purpose of making use of losses.
(2) Flow chart
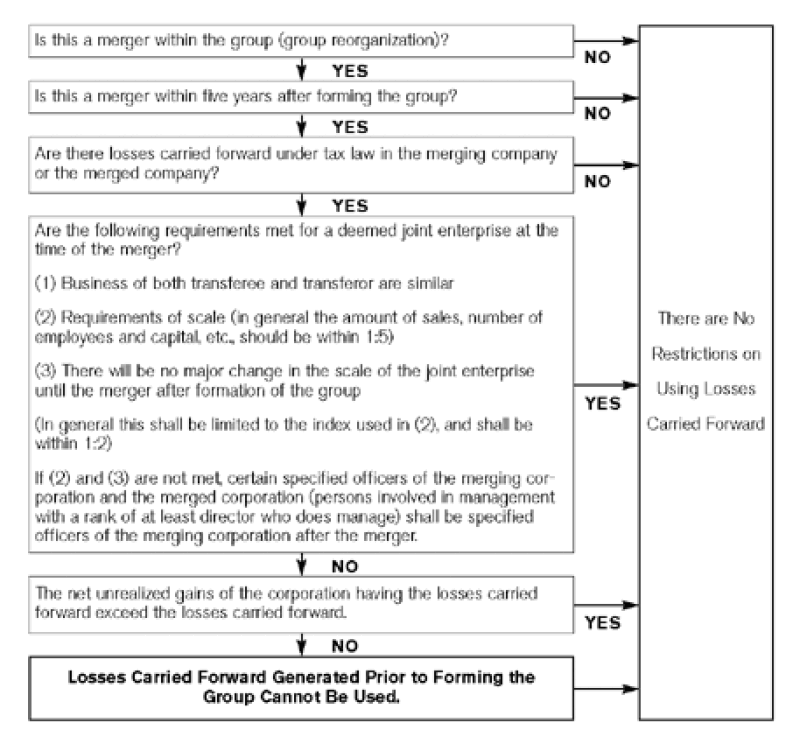
Notes
1. The restriction on carrying forward losses of the merging corporation is a new restriction and applies to fiscal years beginning on or after April 1 2001 (Supplemental Provision section 5(1))
2. The same treatment as above applies to a division in which the transfer or company ceases to exist. In this event, a merger shall be read as a division in which the transfer or company is liquidated.
3. Company A's loss restriction is not only for mergers, but also applies to transfer of division or investment in kind.
Attachment 2
RESTRICTIONS ON USE OF UNREALIZED LOSSES UNDER A QUALIFYING REORGANIZATION (FLOWCHART 2) (CAPITAL LOSS ON SPECIFIED ASSETS)
(1) Basic Concept (section 62-7, section 57(3)(b), (6)(b) of the Law)
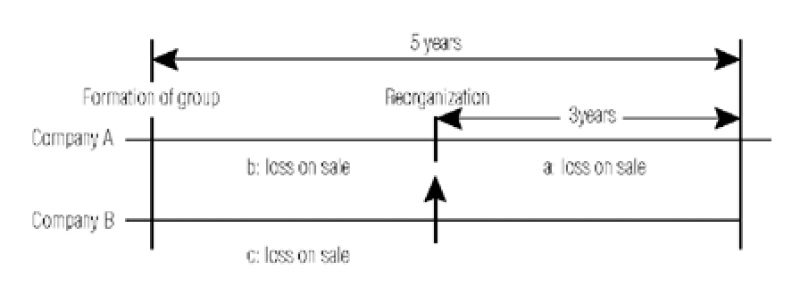
* Case a in the drawing above applies to a merger, division or investment in kind.
* Case b and c in the drawing above applies only to a merger or a division in which the transferor company is extinguished and it constitutes the portion of losses carried forward at the time of the merger, etc
1. In principle if assets with unrealized losses are held prior to forming of the group, and sold after the group is formed with a capital loss realized thereby, the capital loss is not included in calculation of income.
2. However, there is no restriction on the capital loss of assets after five years from forming of the group or three years from the reorganization.
3. The intention is to prevent mergers which are designed for the purpose of making use of unrealized losses.
(2) Flow chart
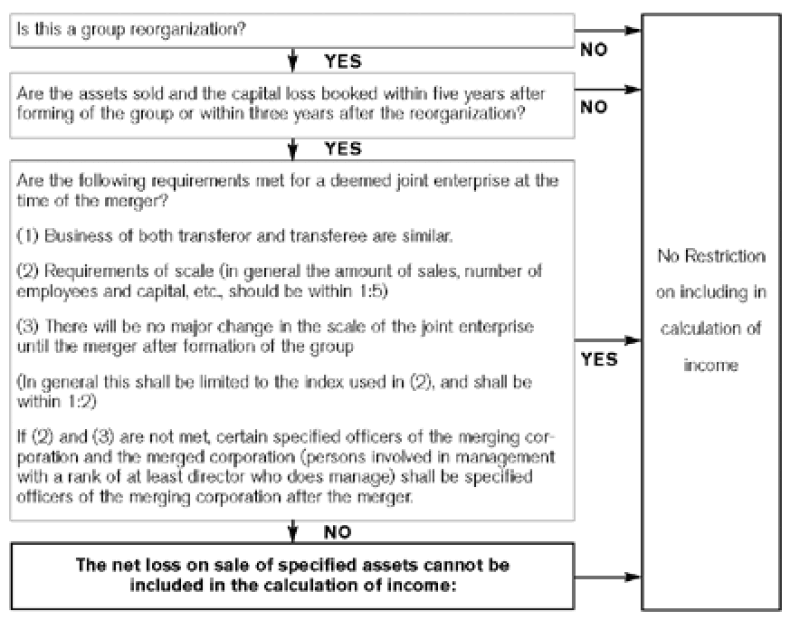
Notes
*Restructuring here only includes a merger, divisions or investment in kind, and does not include a post-establishment transfer.






